Homeowners insurance might not be your desired reading material, yet it is a critical safety net to understand. North Carolina structures home coverage using POLICY TYPES like model numbers. The codes represent policy types designed for particular scenarios.
– NC Homeowner Policy Types:
o HO-2 – Named Perils
o HO-3 – Standard / “special” Form*
o HO-4 – Renter’s Policy
o HO-5 – Comprehensive Form
o HO-6 – Condos
o HE-7 – Extended / “enhanced” form*
o HO-8 – Older Homes
o DP – Dwelling Fire
We will focus in on the HO-3 and the HE-7 in this article, as they are the most prevalent policy types in our state.
As a local independent agency, we are often asked if a standard homeowners policy is “good enough” or whether an enhanced policy is worth considering.
The short answer: it depends on the type of home, risk tolerance, and how much protection is desired
Transparently: We’d like to see everyone who qualifies in an HE-7, but ultimately it is the choice of the client
What Is an HO-3 Policy?
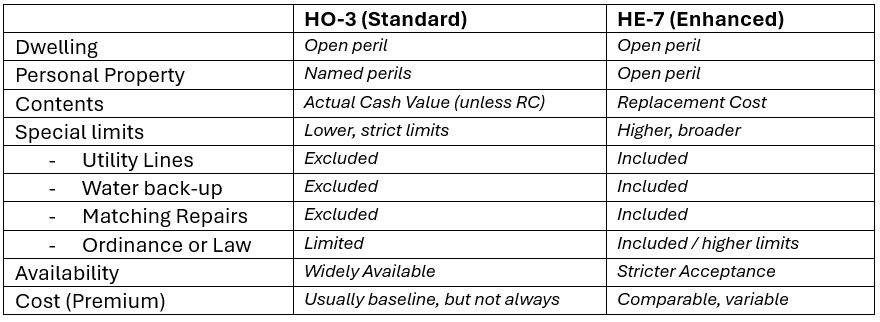
An HO-3 policy is the standard homeowners policy form in North Carolina. It covers the dwelling on an open-peril basis. This indicated that the home is protected unless the cause of loss is specifically excluded. (There is a list of exclusions on these policies)
Personal property, within the HO-3, is covered on a named-perils basis, meaning your belongings are only covered for causes of loss listed in the policy.
Contents coverage is listed at Actual Cash Value (ACV) unless replacement cost (RC) is added or included. ACV indicates that reimbursement for a loss is paid out at the depreciated value. This can leave the individual with a cost gap that will be paid out of pocket.
HO-3 is the baseline option because it offers basic protection at a competitive price point.
What Is an HE-7 Policy?
An HE-7 policy is the enhanced homeowners form available in North Carolina through select carriers. It is designed to provide broader protection than a standard HO-3. The HE-7 policy form is suitable for all homes looking for a conservative approach and highly encouraged for high-value homes.
Coverage for the home itself is structured equally in both the HO-3 and the HE-7. The key variations of the HE-7 are the enhancements and broadening aspects of the policy form.
Enhancements:
Consider the shift for personal property. On the HE-7 it is typically listed on an open peril / replacement cost basis rather than named perils.
Matching of repairs on the home is included, so that the home is reconstructed like-for-like rather than cost-cost. (Particularly useful for ornate homes)
Broadening Aspects:
Special limits are the key area of broadening, and the variety of options is quite extensive. A quality example of effective broadening extends coverage to the utility lines on the property.
HE-7 covers the owner’s utilities lines that run from the house and connect to the main lines at the street. In the HO-3 these lines (gas and water) are excluded.
Other broadening forms can include limits for jewelry, water-back up, and repairs resulting from ordinances and law.
Main Differences Between the HO-3 and the HE-7
Both the HO-3 and HE-7 are designed for homeowners, but vary in the extent to which your belongings are covered. With an HO-3 policy, the home itself may be covered broadly, but personal property is typically limited to named perils unless upgraded. In an HE-7 policy, both the dwelling and personal property are often covered more broadly, reducing the chances of a surprise coverage gap after a loss. HE-7 policies also commonly improve how claims are settled by including replacement cost on contents and offering stronger built-in enhancements than a standard HO-3 form.
Who Should Consider HO-3 vs. HE-7?
HO-3 – Budget conscious homeowners
This individual is okay assuming sharing some risk for personal property, contents, and excluded broad forms, to maximize cash flow. Having an emergency fund as a personal safeguard is always important, but imperative under the HO-3
HE-7 – Coverage conscious and “peace of mind” seeking individuals
The HE-7 policy type offers the best value proposition for individuals who understand their home is likely their largest asset. Risk adverse or high value homeowners want broader protection, replacement cost for higher-value contents, and fewer coverage gaps.
Why Sourcing from an Independent Agency Matters:
Wes Connor Insurance, is an independent insurance agency. We are not limited by a specific company or form type. Instead, we compare options from the market, explain the real-world differences in plain language, and help you weigh price against protection.
With the extensions and additional coverage offered by the HE-7, we often find that it is the product that offers the correct value proposition. However, the right answer depends on the property, the available carriers, and the level of protection you want when a claim happens.
Want to learn more about your specific scenario? We are here to help! Contact our agency to receive guidance at your speed. We want to empower you with knowledge, so the right choice can be made and understood for yourself – Understanding is the real peace of mind.
